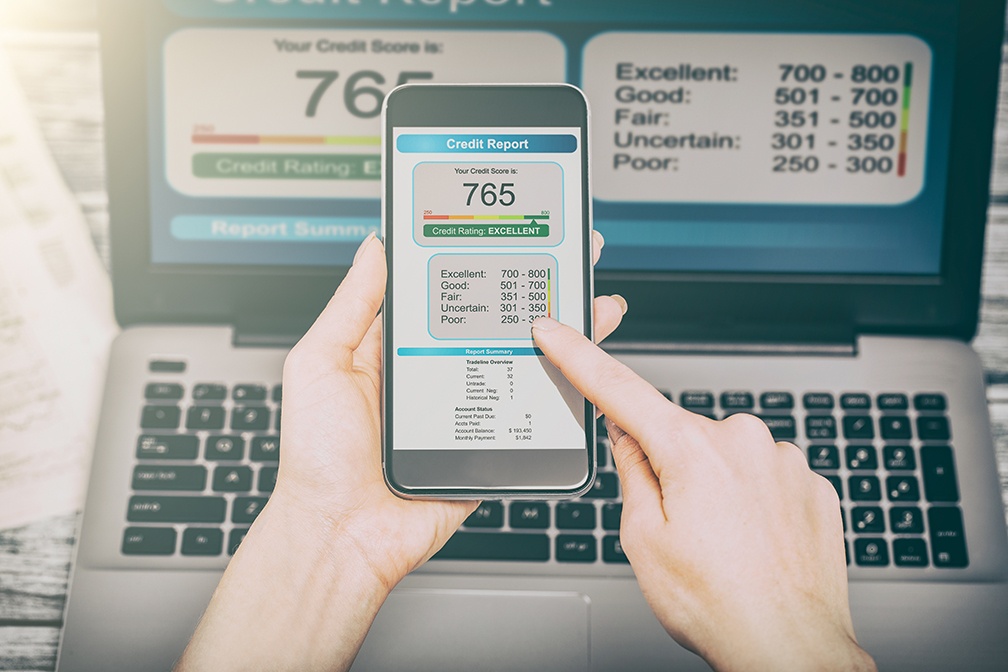
 Whether you’re just out of college, recently married or simply haven’t jumped into the market yet, buying your first home is an exciting prospect. It can also be an expensive one, which is why most people will take out a mortgage to help finance the cost.
If you are planning on engaging with a mortgage lender, you’ll need to have your finances in order. In today’s post, we’ll share a few key reasons why you’ll want to check your credit score well in advance of buying your first home.
Your Credit Score Is A Signal For Lenders
As you know, mortgage lenders have a responsibility to lend to those individuals and families who are at a low risk of default. So when a mortgage lender starts to dig into your financial background, they are looking at your credit history and credit score to help them assess that risk.
Note that having a low score doesn’t necessarily mean you have bad credit. If you’re still in your 20s and have only had a credit card, your score might be low even though you are fully capable of managing a mortgage.
Your Score Impacts Your Mortgage Interest Rate
As mentioned above, your credit score helps to signify your risk. If your credit score is in a lower range, perhaps a 640 or 660, you’re presenting a greater risk than someone with a score of 760 or 800. Because of this, the interest rate that you pay on your mortgage will in part be determined by your credit score. Those individuals who present a higher risk pay a higher rate to compensate. And vice versa, if your credit is spotless you can expect to pay a lower interest rate.
You’ll Need Time To Challenge Any Issues
Finally, you’ll need to give yourself some lead time to challenge any irregularities with your credit report. The credit reporting agencies aren’t perfect and they do make mistakes. There may be some old, retired credit card or other debt sitting on your report which is holding the score down. Even worse, there may be some incorrect delinquency or other error which ends up as a big red flag for potential mortgage lenders.
As you can see, it’s worth spending the time to check your credit score. You get to check it for free once per year, so take advantage of the opportunity. And when you’re ready to discuss buying your first home, contact your trusted mortgage professional. We’ll share how to navigate the credit score and mortgage process so you can land the home of your dreams.
 Most homeowners are so enthusiastic about putting their home on the market and getting the price they’re hoping for that the expenses involved in selling a home are forgotten. However, it’s often said that one has to spend money to make money, and selling a home is no exception! If you’re wondering what kinds of overlooked expenses will cut into your home sale, here are some costs to consider.
 As the housing market continues to evolve, it becomes increasingly crucial for aspiring homeowners to tread carefully and avoid falling into the trap of being house poor. The dream of owning a home should not come at the expense of financial stability and overall well-being. Here are some essential tips to steer clear of this precarious situation:
 When it comes to applying for a mortgage, lenders take various factors into account to determine your eligibility. One crucial aspect they consider is your employment history. Your employment history provides lenders with valuable insights into your financial stability, income consistency, and ability to repay the loan.
 Whether you know a little bit about the market or you’ve sold a home before, you may be considering pricing your own home to avoid the assistance of a real estate agent. However, there are a number of benefits associated with consulting an agent when selling your home. Before making a final decision, consider the following tips.
 Are you planning on using a mortgage to help cover the cost of a new home? If so, you will want to prepare your finances and figure out how you will manage all those wallet-draining monthly expenses. Let’s take a look at how to run a quick financial health check to ensure you are ready to apply for a mortgage.