Sunrise Homes & Renovations, Inc.

  • Home
  • About
    • About Us
    • Recognition
      • Disaster Contractors Network
      • US EPA Certified
    • Accessibility Statement
  • Example Models
  • Renovations
  • Resources
    • First Time Home Buyer Tips
    • First Time Home Seller Tips
  • Blog
  • Contact

Four Mistakes to Avoid When Making an Offer for Your Dream Home

September 27, 2023 by Rhonda Costa

Four Mistakes to Avoid When Making an Offer for Your Dream HomeYou’ve scoured the new home listings, been to all the open houses and have finally found the home of your dreams. It is now time to draft an offer and begin the negotiation process. Below we’ll share four mistakes that you will want to avoid when making an offer on your dream home.

Mistake #1 – Not Working With A Professional

The first mistake that home buyers make is trying to buy a home without using the services of a real estate professional. Buying a home is a significant financial transaction and one where the seller and their agent are working hard to ensure they come out ahead. Having experienced representation on your side of the table ensures that you won’t be taken advantage of.

Mistake #2 – Skipping The Home Inspection

The second mistake – and one that is more common than you think – is skipping the home inspection. There are countless instances of home buyers thinking that the house looks great on the outside without realizing that there are issues with the roof, the foundation, the plumbing, inside the walls or some other area that’s tough to see. Having the house professionally inspected before tabling an offer ensures that issues are fixed up before the transaction is complete. Alternately, if you’re willing to move ahead regardless, you can ask for the price to be reduced as compensation.

Mistake #3 – Not Being Pre-Approved For Financing

The third mistake in our list is making an offer on a home without being pre-approved for the amount of mortgage financing you will need. Regardless of how good your credit is, the mortgage application process is one that can present challenges. Also, many home sellers will require evidence of financing pre-approval before accepting an offer, so it’s best to come prepared.

Mistake #4 – Taking On Other Debts

Once you’ve decided on the home you want to purchase, you will want to avoid taking on any other debts which can affect your credit score. Don’t buy a car, open any new credit cards or do anything else which will show up on your credit report. Once you are pre-approved for your mortgage, you’ll want to keep your credit as spotless as possible to ensure that nothing goes wrong.

If you’re prepared and clear-headed, the offer process will go smoothly and you’ll soon be moving into your dream home. When you’re ready to explore local real estate options, contact your trusted real estate professional.
Filed Under: Home Buyer Tips Tagged With: Buying A Home, Home Buyer Tips, Real Estate Tips

House Hunting: Watch for These Five Small Signs That Can Indicate Much Bigger Problems with a Home

September 22, 2023 by Rhonda Costa

House Hunting: Watch for These Five Small Signs That Can Indicate Much Bigger Problems with a HomeIt’s not uncommon for homebuyers to recount horror stories about properties that appeared to be fine at first glance, but were actually hiding very expensive problems. If you fail to do your due diligence, you might find your dream house turning into a nightmare. The next time you walk through a house, pay attention for these five signs that the property might be hiding a unfortounate secret or two.
Mold, Water Spots and Water Damage

Older and newer homes alike may develop a leaky pipe or another similar plumbing issue from time to time, but any type of water issue can result in mold growth inside the walls. Water spots and warped wood indicate that the property has had a water issue in the past, and this means that the property should be more thoroughly inspected for mold growth before you make a purchase.

Doors and Windows That Stick

One of the most common signs of a foundation issue is doors and windows that stick or that are difficult to open and close. As you walk through the home, open and close the doors at leisure to identify if they are not in the frame properly. The issue should be reviewed by a structural home inspector or foundation contractor.

Small Cracks in the Walls

Some cracks in both interior and exterior walls can indicate that the home’s foundation has shifted and is no longer flat and level. Significant issues may be indicated by molding or door frames that appear to have shifted after installation.

Fresh Paint on a Small Area of the Wall

Many property sellers will apply fresh paint to walls before listing a home for sale, and this is not necessarily a sign of damage to the home. However, when fresh paint is applied on one area of the wall alone, this may be a sign that the homeowner is attempting to conceal water damage or other related issues with the property. Further inspection of the property is in order.

Floors That Slant

Any time a floor slants to a level that you feel as though you are walking up or down across the home, this is a significant indicator that the foundation has shifted. Foundation issues result in the movement of the foundation that the entire home rests on, and this can result in an uneven feeling when you walk across the floor. If you notice that the floors in a property slant, you should schedule an inspection of the foundation.

These small signs are symptoms of large problems, and they should concern you. If you notice any of these problems on a walkthrough, walk away from the home and contact a real estate professional for assistance.

Filed Under: Home Buyer Tips Tagged With: Buying A Home, Home Buying Tips, Home Inspections

Ready to Buy Your First Home? Don’t Forget to Check Your Credit Score – Here’s Why

September 12, 2023 by Rhonda Costa

Ready to Buy Your First Home? Don't Forget to Check Your Credit Score – Here's WhyWhether you’re just out of college, recently married or simply haven’t jumped into the market yet, buying your first home is an exciting prospect. It can also be an expensive one, which is why most people will take out a mortgage to help finance the cost.
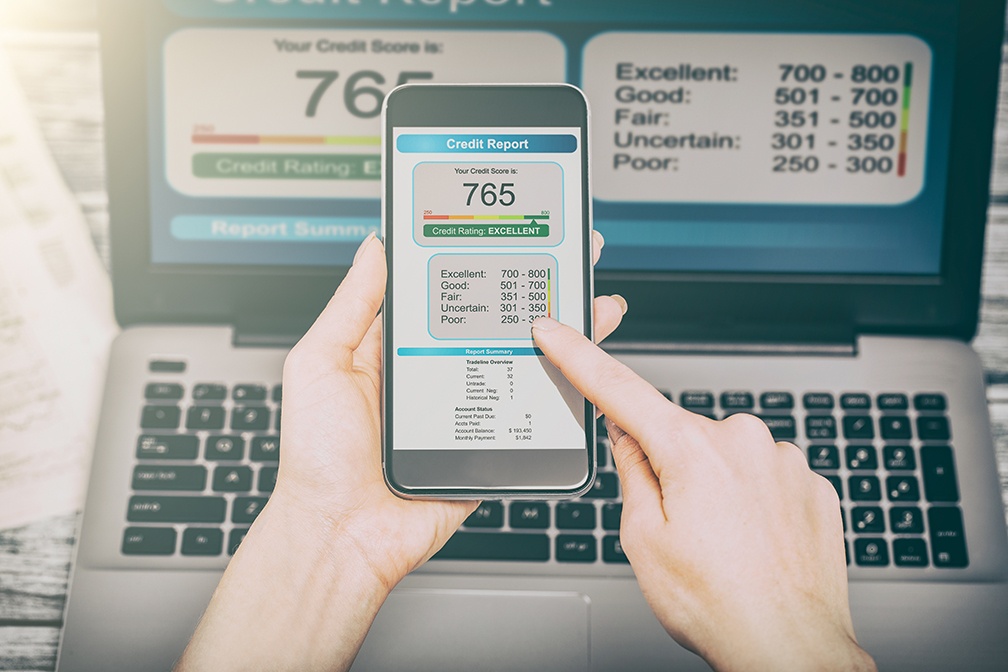
If you are planning on engaging with a mortgage lender, you’ll need to have your finances in order. In today’s post, we’ll share a few key reasons why you’ll want to check your credit score well in advance of buying your first home.

Your Credit Score Is A Signal For Lenders

As you know, mortgage lenders have a responsibility to lend to those individuals and families who are at a low risk of default. So when a mortgage lender starts to dig into your financial background, they are looking at your credit history and credit score to help them assess that risk.

Note that having a low score doesn’t necessarily mean you have bad credit. If you’re still in your 20s and have only had a credit card, your score might be low even though you are fully capable of managing a mortgage.

Your Score Impacts Your Mortgage Interest Rate

As mentioned above, your credit score helps to signify your risk. If your credit score is in a lower range, perhaps a 640 or 660, you’re presenting a greater risk than someone with a score of 760 or 800. Because of this, the interest rate that you pay on your mortgage will in part be determined by your credit score. Those individuals who present a higher risk pay a higher rate to compensate. And vice versa, if your credit is spotless you can expect to pay a lower interest rate.

You’ll Need Time To Challenge Any Issues

Finally, you’ll need to give yourself some lead time to challenge any irregularities with your credit report. The credit reporting agencies aren’t perfect and they do make mistakes. There may be some old, retired credit card or other debt sitting on your report which is holding the score down. Even worse, there may be some incorrect delinquency or other error which ends up as a big red flag for potential mortgage lenders.

As you can see, it’s worth spending the time to check your credit score. You get to check it for free once per year, so take advantage of the opportunity. And when you’re ready to discuss buying your first home, contact your trusted mortgage professional. We’ll share how to navigate the credit score and mortgage process so you can land the home of your dreams.

Filed Under: Home Buyer Tips Tagged With: Buying A Home, Home Buyer Tips, Real Estate Tips

Financial Considerations When Buying a Home

August 4, 2023 by Rhonda Costa

Financial Considerations When Buying a HomePurchasing a home is one of the most significant financial decisions many individuals make in their lifetime. It involves a substantial investment of money and requires careful consideration to ensure long-term financial stability. To navigate the complexities of the home-buying process, it’s essential to be well-informed about the various financial considerations involved. In this blog post, we will explore key factors to consider when buying a home to help you make informed decisions and achieve financial success.
Establishing a Realistic Budget:

Before diving into the home-buying process, it’s crucial to establish a realistic budget based on your financial situation. Consider factors such as your income, existing debts, credit score, and other financial obligations.

Saving for a Down Payment:

Saving for a down payment is a significant aspect of buying a home. Lenders typically require a down payment, which is a percentage of the home’s purchase price. Saving for a substantial down payment not only reduces the overall loan amount but also helps secure better mortgage terms, such as lower interest rates. Aim for a down payment of at least 20% to avoid private mortgage insurance (PMI) and decrease your monthly payments.

Understanding Mortgage Options:

Explore different mortgage options to find the one that suits your financial goals and circumstances. Common types of mortgages include fixed-rate mortgages, adjustable-rate mortgages (ARMs), and government-insured loans. It’s essential to carefully evaluate interest rates, terms, and potential risks associated with each type before deciding.

Considering Closing Costs and Additional Fees:

In addition to the down payment, be prepared for closing costs and other fees associated with purchasing a home. Closing costs typically include expenses like appraisal fees, loan origination fees, title insurance, and attorney fees.

Evaluating Long-Term Affordability:

While you may be able to afford the monthly mortgage payment currently, it’s essential to consider long-term affordability. Consider potential changes in your income, lifestyle, and expenses. Ensure that you have a realistic understanding of how your finances may evolve over time, accounting for future goals like starting a family, education expenses, and retirement planning.

Assessing Property Taxes and Insurance:

Property taxes and homeowners’ insurance are ongoing expenses that come with homeownership. Research the property tax rates in the area where you plan to buy a home and include them in your budget.

Maintaining an Emergency Fund:

Owning a home comes with unforeseen expenses, such as repairs, maintenance, and unexpected emergencies. Aim to have three to six months’ worth of living expenses set aside in an easily accessible savings account.

Getting Pre-Approved for a Mortgage:

Before house hunting, consider getting pre-approved for a mortgage. This process involves a lender reviewing your financial situation and creditworthiness to determine the amount they are willing to lend you. Pre-approval provides a clear understanding of your budget, strengthens your bargaining position with sellers, and speeds up the closing process once you find your dream home.

When buying a home, making well-informed financial decisions is crucial for your long-term financial well-being. Remember to evaluate long-term affordability and maintain a financial cushion to handle unexpected costs. By following these financial considerations, you’ll be better prepared to embark on your homeownership journey and achieve financial success in the long run.

Filed Under: Real Estate Tips Tagged With: Buying A Home, Down Payment, Real Estate

Buying in a New Community: How to Meet and Make Friends with Your New Neighbors

June 16, 2023 by Rhonda Costa

Buying in a New Community: How to Meet and Make Friends with Your New NeighborsOne of the stresses of moving to a new area is giving up the familiarity that you have with your old neighbors and starting from scratch. Whether you’ve just moved to a different locale or you’re planning to relocate in the near future, there are some easy ways that you can make a home of your new neighborhood right from the start.
Stand Up and Smile

While there are neighborhoods where people are definitely friendlier than others, by making your presence positively known you can make an instant impression on those that live around you. When you’re walking around the neighborhood, make sure you use it as an opportunity to engage with your fellow dwellers by throwing a smile in their direction, saying “Good Morning!” or paying attention to their children or their pet. It may not start a conversation right away, but if you see each other a few more times you might soon have a new fast-friend in the neighborhood.

Become a Community Member

If you happen to have a community center specific to your area, it will be even easier to meet the people who live in your neighborhood and make friends with some of them. Look into the offerings of your local center and find some classes or events that appeal to you. Whether it happens to be a craft festival or a fitness class that interests you, this will not only help you meet new people, but will ensure that their interests are aligned with your own so you’ll have some new pals to pursue old hobbies with.

Knock on the Door!

This is definitely the most assertive of options, and seems a throwback to another era, but instead of leaving meeting people up to chance, bake a cake or a batch of cookies and take them over to your new neighbor as a gesture of friendship and kindness. Your neighbors will probably love the baked goods, but this can also be the first step in forming a relationship with them that will come to be one you can both rely on.

When it comes to a new neighborhood, forming new attachments can seem all-but impossible, but there are things you can do to begin a bond right from the start.

Filed Under: Home Buyer Tips Tagged With: Buying A Home, Home Buyer Tips, Moving Tips

Is It Worth It to Put More Than 20 Percent Down?

February 8, 2023 by Rhonda Costa

Down Payments 101: Is It Worth It to Put More Than 20 Percent Down?Are you thinking of buying a new home this spring or summer? If so, you’re not alone. Many thousands of individuals and families alike will become homeowners this year. Whether you’re a first-time buyer or a seasoned veteran of the housing market, you probably know there are significant choices to make. One of the big decisions you will have to ponder is how much you want to invest in your down payment.

With that in mind, let’s try to answer the question of whether or not it is worth it to put more than 20 percent of the home’s price in your down payment.

Ask Yourself: How Liquid Are You?

Before you can decide how much to put down, you first need to determine how liquid your finances are. That is, how much cash do you have access to? For example, if you are considering a $300,000 home, a 20 percent down payment is $60,000. If you have more than $60,000, fantastic. However, if you have less than that, you might have to do a bit of work to save up the remainder.

Even if you do have enough available cash now, you won’t have access to it once you take possession of the home. It is important to leave yourself with some cash in case of emergencies or for other uses.

Higher Down Payment, Lower Interest Rate

If you do choose to invest more than 20 percent in your down payment, it’s possible that you will gain access to a lower interest rate for your mortgage. Many lenders look favorably on homebuyers that are investing more of their own money and borrowing less. Be sure to check with your mortgage advisor to find out if you qualify for lower rates.

Lower Monthly Payments Await

Finally, choosing a down payment higher than 20 percent means that you will have lower monthly mortgage payments in the future. You are borrowing less so you will owe less. This can provide a nice boost to your monthly budget moving forward as you will have more free cash flow each month.

Try to keep in mind that there is no perfect answer to the question of how big your down payment should be. Choosing the best course of action means taking a good, long look at your current financial situation and deciding what your goals are. When you’re ready to discuss buying a new home contact us. Our professional mortgage team is happy to share our experience!

Filed Under: Home Buyer Tips Tagged With: Buying A Home, Down Payments, Home Buyer Tips

  • « Previous Page
  • 1
  • 2
  • 3
  • 4
  • 5
  • …
  • 39
  • Next Page »

Rhonda & Steve Costa

Rhonda & Steve Costa

Call (352) 398-6790
Sunrise Homes & Renovations, Inc.

Contractors License #CBC 1254207

Let’s Keep In Touch!

  • This field is for validation purposes and should be left unchanged.

Connect With Us on Social Media

Categories

Looking For Something?

Our Location


Spring Hill, FL 34608

Equal Housing Opp

Return to top of page

Copyright © 2026 Sunrise Homes & Renovations, Inc.. All rights reserved.   Log In